


Quick Summary: Institutional Dark Liquidity at a Glance
Dark pool trading refers to executing securities orders on alternative trading systems (ATS) or private venues where pre-trade transparency is intentionally restricted. Unlike public stock exchanges-such as the London Stock Exchange (LSE) or the New York Stock Exchange (NYSE)-unlit venues do not publish real-time bid and offer quotes to the wider market.
Institutional asset managers and hedge funds deploy dark pool trading to execute substantial block trades without causing immediate price slippage or signaling intent to predatory participants. While trades remain hidden prior to fill, every execution must eventually be reported to a consolidated tape (such as the FINRA/Nasdaq Trade Reporting Facility in the US or trade repositories under MiFID II in the UK and Europe). Visualisation engines like Bookmap allow independent traders to read the real-time footprints of these transactions across lit books, equalising an uneven playing field.
Alternative Trading Systems Equity Markets: Uncovering Private Liquidity
Alternative trading systems (ATS) are non-exchange trading venues that bring together buyers and sellers of securities under statutory frameworks. Regulated by bodies like the US Securities and Exchange Commission (SEC) and the UK Financial Conduct Authority (FCA), ATS networks handle a significant percentage of consolidated equity volume.
+———————————————————————–+
| Consolidated Equity Flow |
+———————————–+———————————–+
|
+———————–+———————–+
| |
v v
[ Lit Exchanges ] [ Dark Liquidity (ATS) ]
– Public pre-trade quotes – Hidden order books
– Displayed bid/ask queue – Midpoint matching engines
– Immediate price impact – Minimal market footprint
| |
+———————–+———————–+
|
v
[ Consolidated Tape Reporting ]
(Trade prints post-execution)
In lit markets, order flow appears openly in depth-of-market (DOM) tables. Large limit orders rest visibly, allowing rival market participants to reprice ahead of the trade. ATS equity platforms solve this transparency penalty by replacing public quotes with blind matching protocols. Rather than bidding up shares on an open exchange, institutional desks send orders into private liquidity reservoirs to find opposing natural interest safely.
Off-Exchange Private Securities Matching: How Orders Clear Away from Public Bourses
Off-exchange matching operates on automated crossing systems that pair buy and sell interests without publicly exposing the order size or identity of either party. These operations fall broadly into three operational models:
- Continuous Crossing Engines: Orders enter an electronic buffer and execute automatically as matching parameters (price, volume, contra-party restrictions) intersect.
- Scheduled Call Auctions: Orders accumulate over a specified time window and match simultaneously at a single clearing price calculated to maximise executable volume.
- Firm Quote and Indication of Interest (IOI) Systems: Algorithmic systems route targeted indications to vetted market participants to query potential liquidity matches before committing capital.
By matching institutional block orders away from displayed exchange floors, funds prevent front-running, control friction, and preserve execution performance across benchmark targets like Volume-Weighted Average Price (VWAP).
Unlit Order Book Stock Execution: Market Impact and Hidden Depth
When a mutual fund liquidates 500,000 shares of a mid-cap stock on an open exchange, the immediate arrival of that volume overwhelms available bid depth. Market makers drop their bids, market algorithms step back, and the fund incurs substantial execution slippage.
Unlit order books eliminate pre-trade market impact:
- Pre-Trade Concealment: The order remains invisible to external feeds while resting on the ATS matching engine.
- Algorithmic Discretion: Resting parent orders break down into smaller child executions according to liquidity availability.
- Zero Adverse Queuing: The absence of a public quote queue prevents rival market participants from placing tactical bids directly in front of the institutional order.
However, executions in unlit books still leave structural footprints. As volume clears off-exchange, liquidity shifts on displayed exchanges. Tracking market depth and trade volume dynamics via Bookmap provides visual confirmation of when large orders absorb inventory across consolidated markets.
Hidden Liquidity Trading Venues: The Architecture of Dark Pools
Modern hidden liquidity venues rely on complex architectural infrastructures designed to manage risk, ensure low-latency connectivity, and balance participant flow.
| Feature | Lit Public Exchanges | Dark Pool Venues (ATS) |
| Pre-Trade Transparency | Full (Bids, Asks, Order Depth visible) | None (Blind order submission) |
| Post-Trade Transparency | Instantaneous public tape report | Real-time consolidated reporting post-fill |
| Pricing Mechanism | Continuous double auction, spread based | Derived pricing (often NBBO midpoint) |
| Access Restrictions | Broad public and retail broker access | Tiered institutional membership, routing filters |
| Primary Goal | Price discovery and capital formation | Minimisation of transaction cost and slippage |
Matching engines inside private venues routinely reference the National Best Bid and Offer (NBBO) or local exchange best prices, referencing displayed markets to determine the legal execution bounds for non-displayed trades.
Financial Market Microstructure Overview: Lit Exchanges vs. Unlit Venues
Understanding the modern market microstructure requires analysing the relationship between lit and unlit equity venues. Market microstructure evaluates how exchange rules, order routing protocols, and participant types translate latent demand into realised transactions.
Lit markets perform the vital civic role of public price discovery. Every displayed quote establishes supply and demand curves for the broader financial system. Unlit venues, by contrast, act as pure liquidity processors. Because most dark venues price their matches off the NBBO established by lit books, they are entirely dependent on public exchanges for baseline valuation metrics.
When trading volume tips too heavily toward unlit venues, the quality of lit price discovery degrades. Spreads can widen on displayed exchanges, leading regulators worldwide to enact structural caps on non-transparent volume.
Institutional Securities Exchange Mechanisms: Continuous Books, Auctions, and Block Crosses
Institutional desks handle execution mandates through distinct structural mechanisms:
- Continuous Limit Books: Orders are matched sequentially based on price-time priority or size-pro-rata rules as soon as matching liquidity arrives.
- Conditional Matching Auctions: Desks place “conditional orders” across multiple venues simultaneously. When one ATS locates a potential contra match, it alerts the routing algorithm to drop equivalent exposure in secondary venues, mitigating the risk of accidental double-fills.
- Direct Block Crosses: Facilitated via specialized block trading ATS platforms where minimum trade thresholds (often 10,000 shares or £100,000+ notional value) ensure only institutional participants can interact.
These diverse matching protocols allow portfolio managers to source liquidity without exposing their hand to fast electronic counterparties.
Wholesale Equity Market Routing Architectures: Smart Order Routers and Internalisation
Retail brokers and wholesale liquidity providers interact via specialised routing architectures designed to optimise order execution quality. When an individual submits a retail market order, it rarely travels straight to a lit exchange floor.
Instead, broker Smart Order Routers (SORs) evaluate execution probabilities across lit exchanges, retail market makers, and ATS networks:
[ Retail / Institutional Order ]
│
▼
[ Smart Order Router (SOR) ]
├──> Internaliser / Wholesaler (Fills at NBBO or better)
├──> Dark ATS / Crossing Network (Checks unlit midpoint)
└──> Lit Exchange Routing (Sweeps displayed book depth)
Through internalisation, wholesale market-making firms purchase retail order flow directly. Because retail flow is statistically balanced and rarely represents toxic institutional positioning, wholesalers match it internally, granting modest price improvements relative to the lit NBBO while keeping trades off public lit order books.
Broker-Dealer Owned Crossing Networks vs. Independent ATS
Dark pools fall into two primary commercial categories, each presenting distinct execution profiles and conflict-of-interest considerations:
Broker-Dealer Owned Crossing Networks
Operated by global investment banks, these networks cross client order flow against internal inventory, institutional clients, and affiliate trading desks.
- Examples: Goldman Sachs (Sigma X), Morgan Stanley (MS POOL), UBS (PIN).
- Operational Profile: Banks generate revenue from commissions and bid-ask capture. However, conflicts can emerge if the broker’s proprietary trading desk interacts with external customer orders.
Independent ATS Venues
Independent venues operate without affiliated proprietary trading desks, positioning themselves as neutral meeting places for institutional capital.
- Examples: Liquidnet, Instinet.
- Operational Profile: Often focused on large institutional block crosses, these venues feature strict participant tiers and higher minimum execution thresholds, insulating asset managers from speculative flow.
Midpoint Cross Execution on Sigma X and Peer Venues
A core operational feature within broker-dealer venues like Sigma X is the midpoint cross. Rather than forcing buyers to lift the offer or sellers to hit the bid, the matching engine calculates the exact midpoint between the consolidated best bid and best offer.
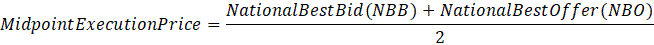
If stock XYZ displays a lit market of £50.00 Bid / £50.10 Offer:
- A buyer on a lit venue pays £50.10.
- A seller on a lit venue receives £50.00.
- Inside a midpoint dark pool, both parties execute at £50.05.
Both counter-parties save half the spread (£0.05 per share), generating substantial aggregate cost savings on multimillion-share institutional orders.
Predatory HFT Latency Arbitrage Inside Private Venues
While designed as safe harbors for large orders, dark pools are not immune to predatory trading strategies. High-Frequency Trading (HFT) firms utilize microwave networks and colocation facilities to exploit microscopic time differentials between public quote updates and dark venue calculations.
1. Lit Market Quotes Shift
[ Lit Exchange updates: Bid moves from £50.00 -> £50.04 ]
│
▼ (Microsecond network latency gap)
2. ATS Pricing Lags
[ Dark Pool Engine still references stale £50.00 Bid ]
│
▼
3. Latency Arbitrageur Strikes
[ HFT buys at stale £50.02 midpoint in dark pool; instantly sells at £50.04 lit offer ]
This phenomenon-latency arbitrage-occurs when an unlit venue’s matching engine relies on a direct feed or consolidated SIP feed that updates microseconds slower than the HFT firm’s proprietary market connection. To combat this, modern ATS operators implement synthetic “speed bumps” and randomised order delays to negate speed advantages.
Form ATS-N Disclosure Requirements for Investment Banks
Historically criticised for opaque operational practices, US-based alternative trading systems are subject to strict regulatory transparency rules under SEC Rule 304 of Regulation ATS. Operators must publicly file and maintain Form ATS-N.
Form ATS-N filings require comprehensive disclosure regarding:
- The operational identity of the broker-dealer operator and affiliate trading access.
- Specific order types, matching priorities, and routing logic.
- Fee structures, tier rebates, and volume discounts.
- Data feeds used for pricing (e.g., direct exchange feeds vs. consolidated SIP).
- Protocols governing subscriber segmentation and potential counter-party exclusion.
These filings provide portfolio managers and institutional compliance officers with complete operational visibility into how their order flow is handled and cleared.
Top 6 Ways Traders Detect Dark Pool Footprints on Lit Books
Retail and proprietary traders cannot see orders sitting unexecuted inside a private ATS. However, the downstream impact of large trades inevitably ripples onto lit exchange books.
- Volume Imbalances on the Tape: Clusters of off-exchange prints appearing on the consolidated tape at identical prices indicate continuous ATS fill activity.
- Hidden Iceberg Executions: Visible limit orders that repeatedly refill at the same price point demonstrate institutional accumulation or distribution absorbing contra flow.
- Ghost Liquidity Absorption: Sudden liquidity vanishings on the lit book without corresponding lit prints often mean an algorithm rerouted an aggressive block order to an unlit venue.
- Order Book Heatmap Densities: Advanced volume visualisation reveals resting liquidity shelves that institutional algorithms defend or target after off-exchange block crosses.
- Cumulative Volume Delta (CVD) Divergence: A clear divergence between price movement and aggressive market order volume frequently highlights passive institutional absorption occurring off-exchange.
- Block Trade Velocity Surges: High-notional-value prints registering on Trade Reporting Facilities (TRFs) within milliseconds provide immediate directional bias regarding institutional positioning.
Why Choose Bookmap: Level 10 Market Transparency
Navigating complex markets influenced by hidden institutional order flow requires software built specifically for market microstructure visualization. Bookmap delivers unmatched visibility into order flow, transforming raw market depth and fragmented trade feeds into an intuitive visual workspace.
Visualise True Liquidity With Bookmap
+—————————————————-+
| Price |
| ▲ |
| │ ░░░░░░░░░░░░░░░░░░░░░░ [Resting Liquidity] |
| │ ●● (Aggressive Buys) |
| │ ────●●●●───────────────── [Trade Prints] |
| │ ●● (Aggressive Sells) |
| │ ░░░░░░░░░░░░░░░░░░░░░░ [Iceberg Absorption]|
| └──────────────────────────────────────────────► |
| Timeline |
+—————————————————-+
Unmatched Analytical Depth
While conventional charting packages summarize market activity into static Japanese candlesticks, Bookmap renders every Level 2 quote update and Level 3 market event at millisecond precision. Watch liquidity build, shift, pull, and execute in real time.
Proven Empirical Results
Professional proprietary traders, hedge fund execution analysts, and active retail traders rely on Bookmap to eliminate blind spots. By observing how lit limit books react to institutional block executions, users routinely reduce slippage, avoid bull/bear traps, and validate trade setups with objective liquidity data.
Proprietary Heatmap and Volume Dots
Bookmap’s signature depth-of-market heatmap visualises resting limit orders over time, while dynamically sized Volume Dots reveal precisely who is hitting the bid or lifting the offer. Identify hidden iceberg orders and institutional absorption zones the second they materialise.
High-Speed Data Architecture
Powered by direct, high-frequency broker integrations and dedicated low-latency market data connections, Bookmap processes tens of thousands of market events per second without freezing or lagging during peak market volatility.
Backed by Trader Acclaim
With an “Excellent” rating on Trustpilot based on hundreds of independent trader reviews, Bookmap is globally recognised for product reliability, advanced analytical features, and exceptional educational support.
Platform Plans and Transparent Pricing
Bookmap offers scalable subscription tiers tailored to every stage of a trader’s development, from foundational crypto order flow tracking to multi-asset institutional execution.
| Plan Tier | Pricing (Monthly / Annual) | Supported Asset Classes | Key Capabilities & Inclusions |
| Digital | Free ($0) | Crypto (Real-time feeds) | Base order book heatmap, real-time crypto connections, volume dots. |
| Digital+ | $19/mo (or $16/mo billed annually) | Crypto | Advanced crypto data feeds, customizable indicators, extended visual depth. |
| Global | $49/mo (or $39/mo billed annually) | Stocks, Futures, Crypto | Full Level 2 depth visualization, multi-asset data routing, audio volume alerts. |
| Global+ | $99/mo (or $79/mo billed annually) | Stocks, Futures, Crypto | One-click chart trading, automated iceberg detection, full API access, live trading sessions. |
Note: Real-time stock and futures exchange market data feeds (e.g., CME, Nasdaq, dxFeed) are connected directly via supported brokerages or purchased as separate third-party data subscriptions.
Transform Your Market Perception Today
Stop trading with static, lagging indicators. Uncover true market depth, track institutional footprints, and execute with precision.
- [Get Started with Bookmap Free] – Explore live crypto order books instantly.
- [Book a Platform Demo Consultation] – See how Bookmap identifies institutional absorption in real time.
- [Speak to a Market Data Expert] – Match your trading style with the ideal data feed and connection architecture.
Dark Pool Trading FAQ: Key Insights Answered
How do institutional brokers execute block orders anonymously?
Institutional brokers utilise Smart Order Routers (SORs) coupled with algorithmic execution systems such as TWAP (Time-Weighted Average Price) or VWAP (Volume-Weighted Average Price). These algorithms break massive parent orders into hundreds of non-displayed child orders distributed across independent ATS platforms, internal crossing engines, and dark venues. Orders rest without public quotation and match passively against midpoint prices, concealing the institution’s true size and identity.
What regulatory scrutiny exists under SEC ATS rules?
In the US, alternative trading systems operate under Regulation ATS. Following concerns over market fairness and conflicts of interest, the SEC introduced Rule 304, mandating exhaustive Form ATS-N filings. Regulators scrutinise how broker-dealers route orders, whether proprietary desks receive preferential execution priority, the latency of pricing data feeds, and subscriber classification systems to prevent discriminatory trading practices. Similar frameworks exist in the UK and EU under FCA guidelines and MiFID II volume caps.
Can retail investors access dark liquidity pools?
Retail investors cannot directly route manual orders to private institutional dark pools. Instead, retail brokers automatically route customer market and limit orders to internalising wholesalers or ATS venues via internal smart routing protocols. While retail participants cannot sit directly on an institutional crossing book, their orders frequently receive price improvement within these venues relative to displayed exchange quotes.
What impact does unlit trading have on public price discovery?
When a high percentage of equity volume matches away from public exchanges, lit market liquidity thins. This fragmentation can lead to wider displayed bid-ask spreads, increased volatility during sudden order sweeps, and reduced efficiency in the public pricing of corporate assets. Regulators continuously review the balance between pre-trade confidentiality for institutions and robust price discovery for the general public.
Are you looking for regulatory mechanics, trading mechanics, or market impact analysis?
Understanding dark pools requires mastering all three facets:
- Trading Mechanics: Midpoint crossing networks, continuous limit books, and conditional orders.
- Regulatory Mechanics: Compliance with SEC Form ATS-N disclosures, FINRA reporting, and FCA/MiFID II caps.
- Market Impact Analysis: How off-exchange prints reshape resting depth, absorb inventory, and influence lit exchange order books.
Visualisation platforms like Bookmap bridge these areas by showing precisely how off-exchange volume influences displayed market action.
Do you need specific examples of operating broker-dealer crossing networks?
Prominent active broker-dealer crossing networks include Goldman Sachs’ Sigma X, Morgan Stanley’s MS POOL, UBS’s PIN, and JPMorgan’s JPM-X. These private networks primarily cross client orders against non-conflicting internal and external liquidity at derived market midpoints.
Are you analysing equity dark pools or crypto off-chain liquidity?
While dark pools originated within equity microstructures to facilitate institutional block transfers, off-chain liquidity mechanisms have expanded rapidly into digital assets. Crypto markets deploy over-the-counter (OTC) institutional desks, private RFQ (Request for Quote) engines, and decentralized dark pools utilizing zero-knowledge proofs (zk-SNARKs) to clear multi-million-dollar token blocks without disrupting public automated market maker (AMM) pools or centralized exchange order books.