


Moving money between two African countries can sometimes be more complicated than sending it to another continent. A payment made in one African market may pass through financial institutions outside the continent before reaching its destination, adding time, costs, and unnecessary intermediaries.
Redtech, a Nigerian payments technology company, wants to change that by building a digital payments bridge connecting Kenya and Nigeria, with ambitions to extend the infrastructure across Africa.
The company sees an opportunity to make cross-border transactions easier for individuals and businesses that trade across African markets.
Speaking to Techweez, Redtech’s CEO, Emmanuel Ojo, described the ambition as creating a link between Nigeria’s more than 200 million people and Kenya’s roughly 58 million, open to individuals and small businesses alike, with the longer-term aim of letting a company operate in several African markets without starting from scratch in each one.
Redtech’s longer-term vision is creating a common digital payment highway between African markets, instead of forcing every business to navigate a different road network whenever it crosses a border.
Why Money Moves Slowly Between African Countries
Africa has made considerable progress in domestic digital payments, but connecting these systems remains a challenge.
The trouble, according to Ojo, lies less in the money than in the plumbing. Payment systems in different countries talk to each other through software connections known as APIs, and when two systems follow different technical standards, a transaction can fail even though both countries have working digital payments.
It resembles two railways built with different track widths, where cargo has to be unloaded and reloaded at the border, and every handover adds time and cost.
Settlement times add to the delay, with Ojo saying some markets settle within 24 hours while others take three or four days. He also said transfers between African countries can end up passing through the United States or Europe before returning to the continent, a detour he says can stretch a payment to as long as three days.
Onboarding is the other sore spot. A business that expands into a new country usually has to register, get verified, and pass due diligence checks again with each new payment provider, much like queueing at every border post with the same paperwork. Redtech says it wants companies to go through that process once, using a single connection that would eventually serve all 54 African countries.
A $20 Billion Track Record
Redtech is positioning its existing payment processing experience as an important foundation for this expansion.
Its CEO says the company processed more than $20 billion worth of transactions in 2025, equivalent to approximately ₦30 trillion. To expand quickly, the company is relying on partners rather than building everywhere at once.
Its partnership with United Bank for Africa gives it a route into 20 African markets, according to Ojo, and the plan is to open its own legal entities and pursue licenses country by country afterwards, a process he says can take a year or more in some markets. Redtech has previously said it is targeting 29 African markets with acquisitions on the table and has been reported to be weighing a $100 million raise to fund it.
Stepping Into a Mobile Money Market
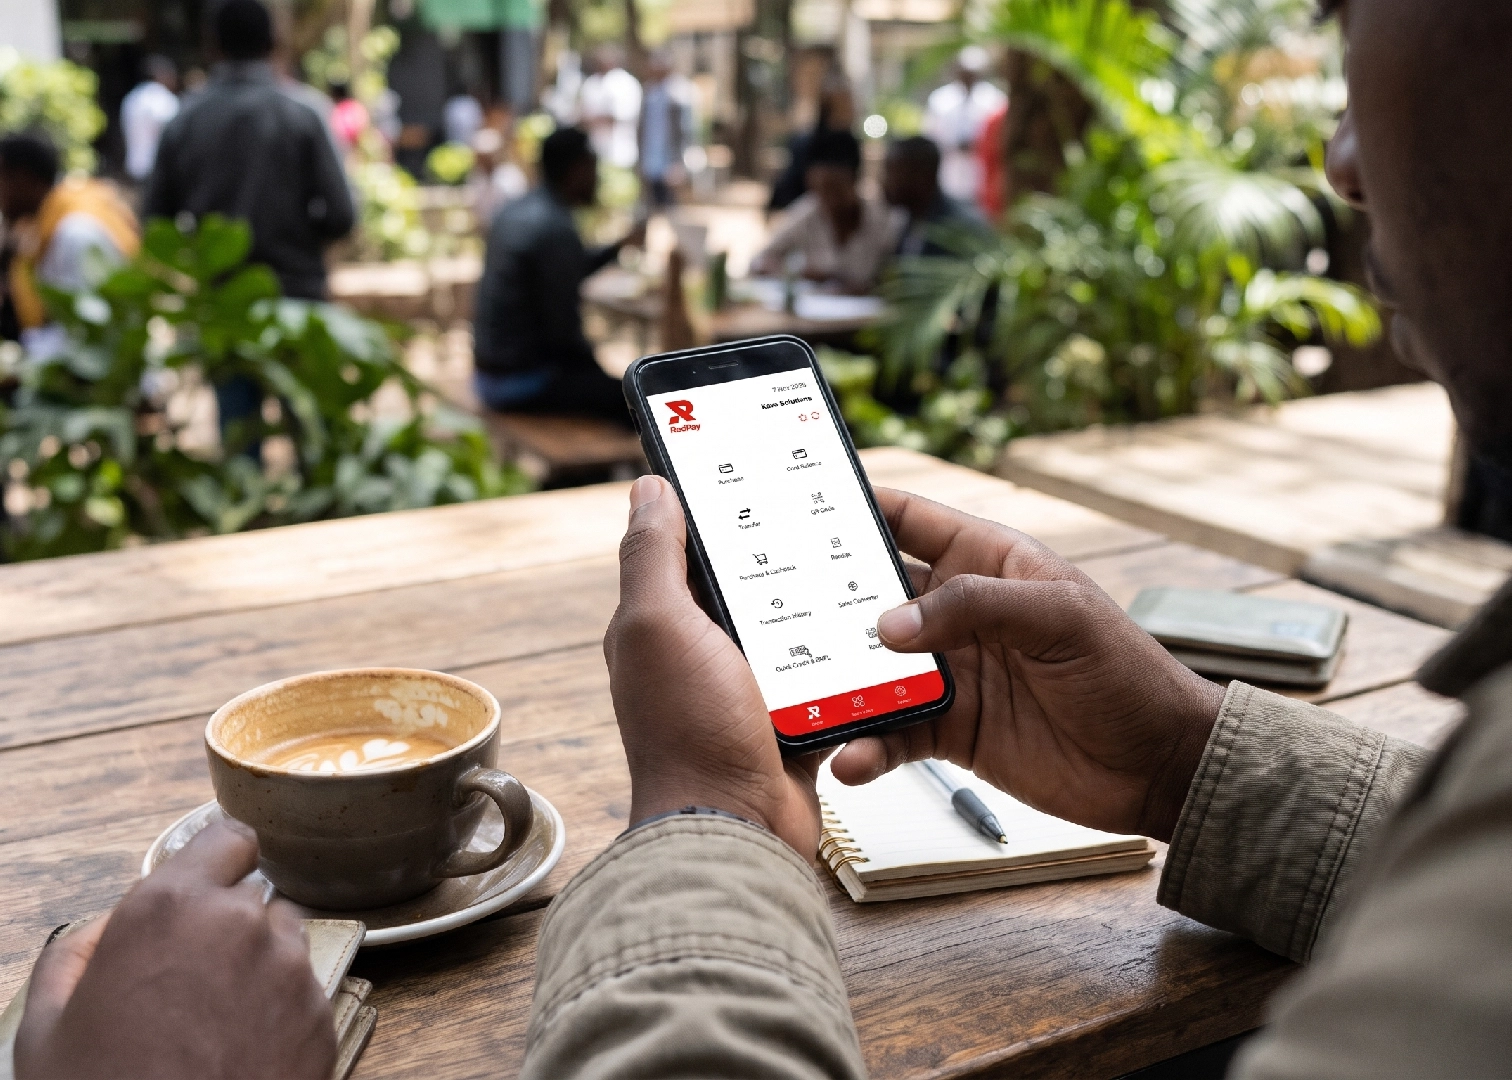
Kenya will not reward a copy of the Nigerian model, where cards, point-of-sale machines, and USSD codes carry much of the load. Mobile money does that job here, with M-Pesa holding about 89% of mobile money subscriptions, and businesses already use it to collect from customers and pay suppliers.
“We have to recognize and respect the preferences of consumers in every market. It is not going to be a copy-and-paste approach. In Nigeria, people use USSD a lot. In some Asian markets, people use QR codes heavily. In the Kenyan market, there is a high affinity for mobile money payment options.”
Redtech’s plan is to start with payment and collection tools for micro, small, and medium businesses, and Ojo described the company as entering through an underserved segment rather than challenging the dominant player head on.
There is room to test that claim, because the alternatives are shifting, with the value of card payments in Kenya falling 11.55% in the six months to June 2026, according to the Nation, as changing payment habits and a weaker economy weighed on spending. Cross-border payments remain one of the clearer gaps a newcomer could try to fill.
A Trial Run With No License Details Yet
Ojo said Kenya’s first product would launch by the first quarter of 2027 at the latest, as a limited first step through partners rather than a full rollout.
“For now, we are testing the waters. We have a solution that should be launched by Q1 2027 at the latest.”
Redtech has not yet unveiled its Kenyan partners, and it has yet to disclose the status of its regulatory engagement with the Central Bank of Kenya or whether it has applied for the necessary authorizations.
For Kenyan businesses that buy from or sell to Nigeria, cheaper and quicker payments would ease the cost of getting paid, settling suppliers, and entering new markets.
A corridor like this depends on agreements between banks, compatible systems, regulators willing to cooperate, and settlement that arrives on time, much of which sits beyond one company’s control.